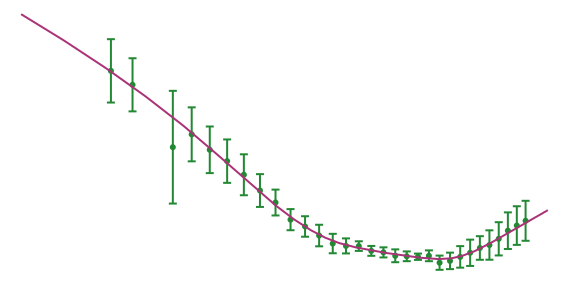
GOOG · 21 Jul 2025 vol
A Complete Quant Stack
Our Product Suite
Core Analytics
Pricer
Vola Dynamics Pricer — super-fast and robust pricing of European and American vanillas, with accurate handling of cash dividends. Full Greeks including delta, gamma, vega, volga, vanna, rho, and theta.
Fitter
Vola Dynamics Fitter produces stable, arbitrage-free volatility surfaces using Bayesian methods. Fits the entire US options universe on one box — equities, ETFs, indices, and futures.
Curves
Vola Dynamics Curves — intuitive and flexible parametric vol curves, way beyond simple curves like SABR, SSVI, and SVI. Bias-free fits of all observed market vol shapes including W-shaped curves around earnings.
Optional Modules
PnL Explanation
Vola Dynamics PnL Explanation module decomposes profit and loss for vanilla and volatility derivatives into ATM-forward, skew, and curvature components using Greeks or scenarios.
Vol Derivatives
Vola Dynamics Vol Derivatives — fast pricing of var and vol swaps (capped or uncapped), options on var and vol, and corridor/conditional variance. Consistent hedging with vanillas under shared spot-vol dynamics.
VIX Pricer
Vola Dynamics VIX Pricer — VIX future valuation based on SPX and VIX vol surfaces. VIX futures Greeks with respect to SPX (BS or adjusted with spot-vol dynamics).
Discount Curve Fitter
Vola Dynamics Discount Curve Fitter — imply the discount curve used by the options market from index option prices, using one or more snapshots. Handles general term-structure shapes including inverted yield curves.
Div Fitter
Vola Dynamics Dividend Fitter — imply cash dividend amounts consistent with market prices. Detect market dividend moves and backfill historical data.
Event Var Fitter
Vola Dynamics Event Variance Fitter — calibrate the additional event variance associated with earnings, elections, and other events. Important for accurate American option pricing and trading strategies.
Event Modeling
Vola Dynamics Event Modeling — given a dirty vol surface, calibrate its decomposition into event jumps and a clean vol surface, and vice versa. For earnings, FOMC, elections, and other scheduled events.
FX Module
Vola Dynamics FX Module — handles all FX-specific conventions for delta, premium type, and ATM/risk-reversal/butterfly definitions.