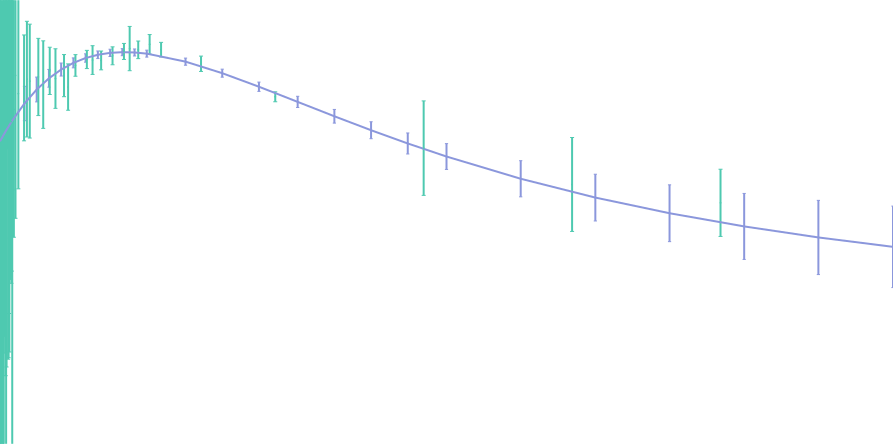
SPIBOR · 14 Feb 2023 rate
Module
Discount Curve Fitter
- Calibration of the discount curve from index option prices, e.g. SPX or SX5E.
- Combine market data from multiple indexes and times to calibrate a stable discount curve with error bars.
- Fit implied discount rates to parametric term-structure to allow robust calibration (even from one market snapshot).
- Handles a variety of term-structure shapes, including inverted yield curves (e.g. via Nelson-Siegel).