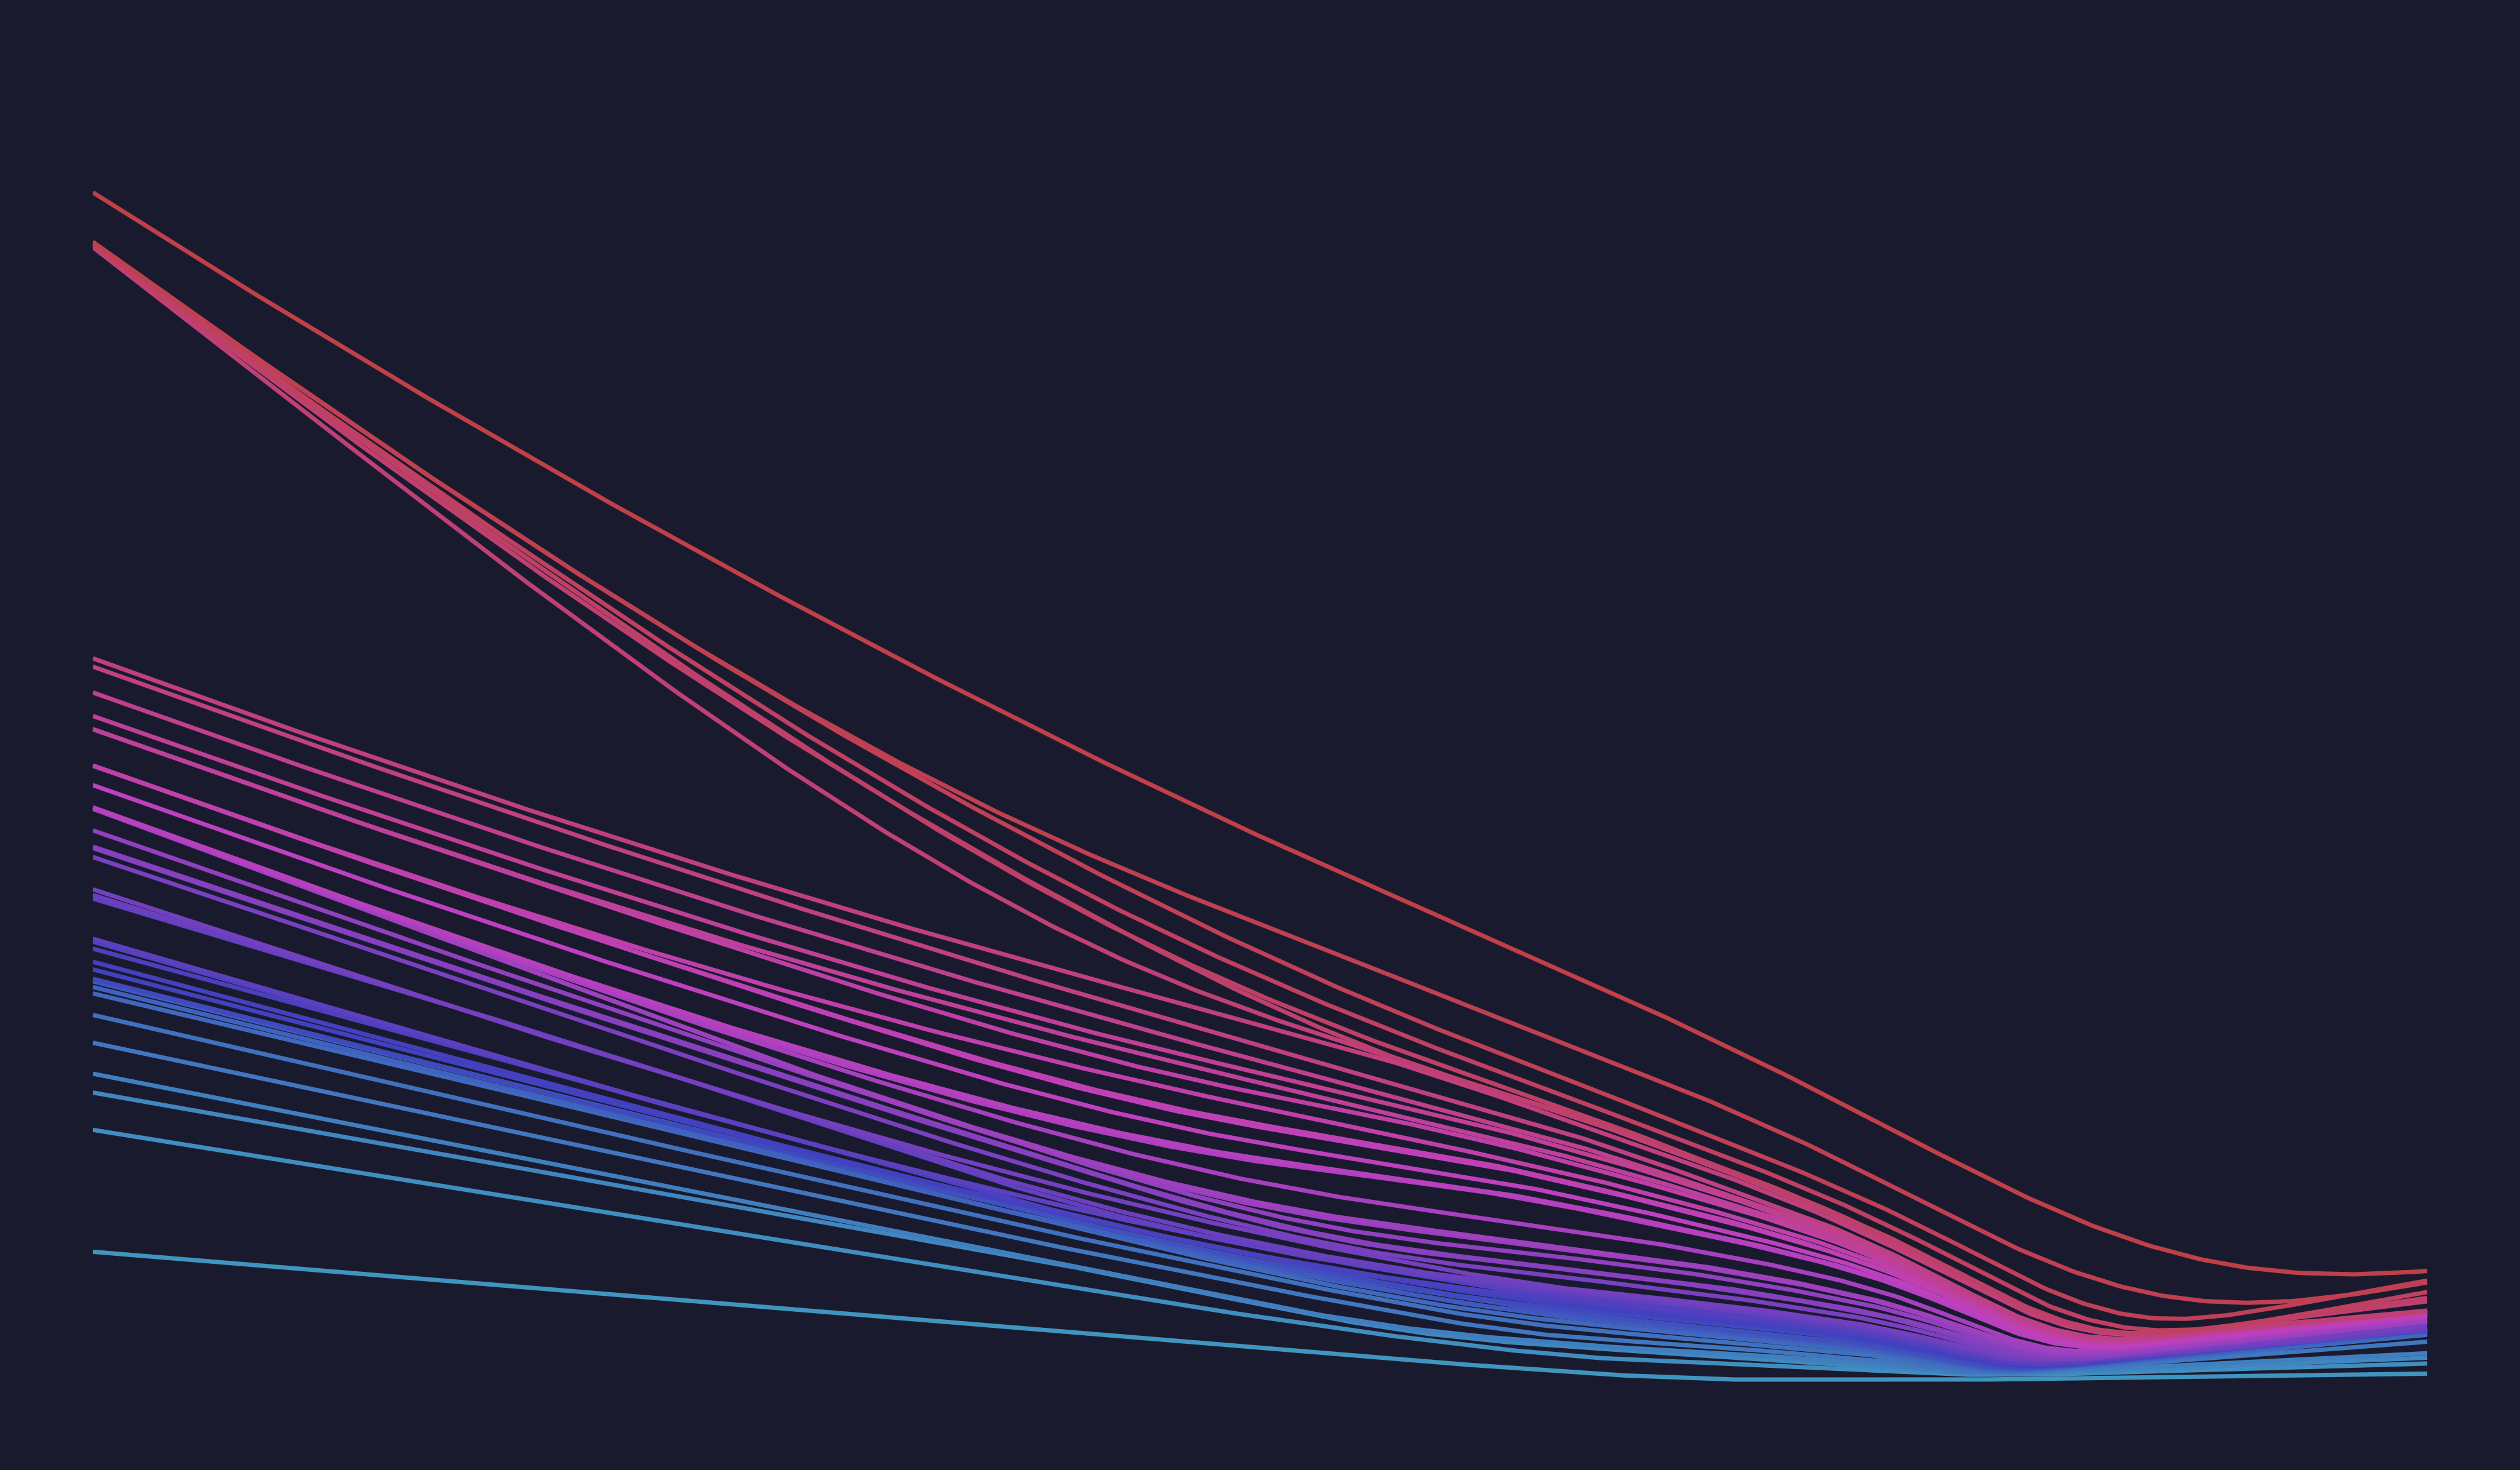
Examples: Equities, Indices & Futures

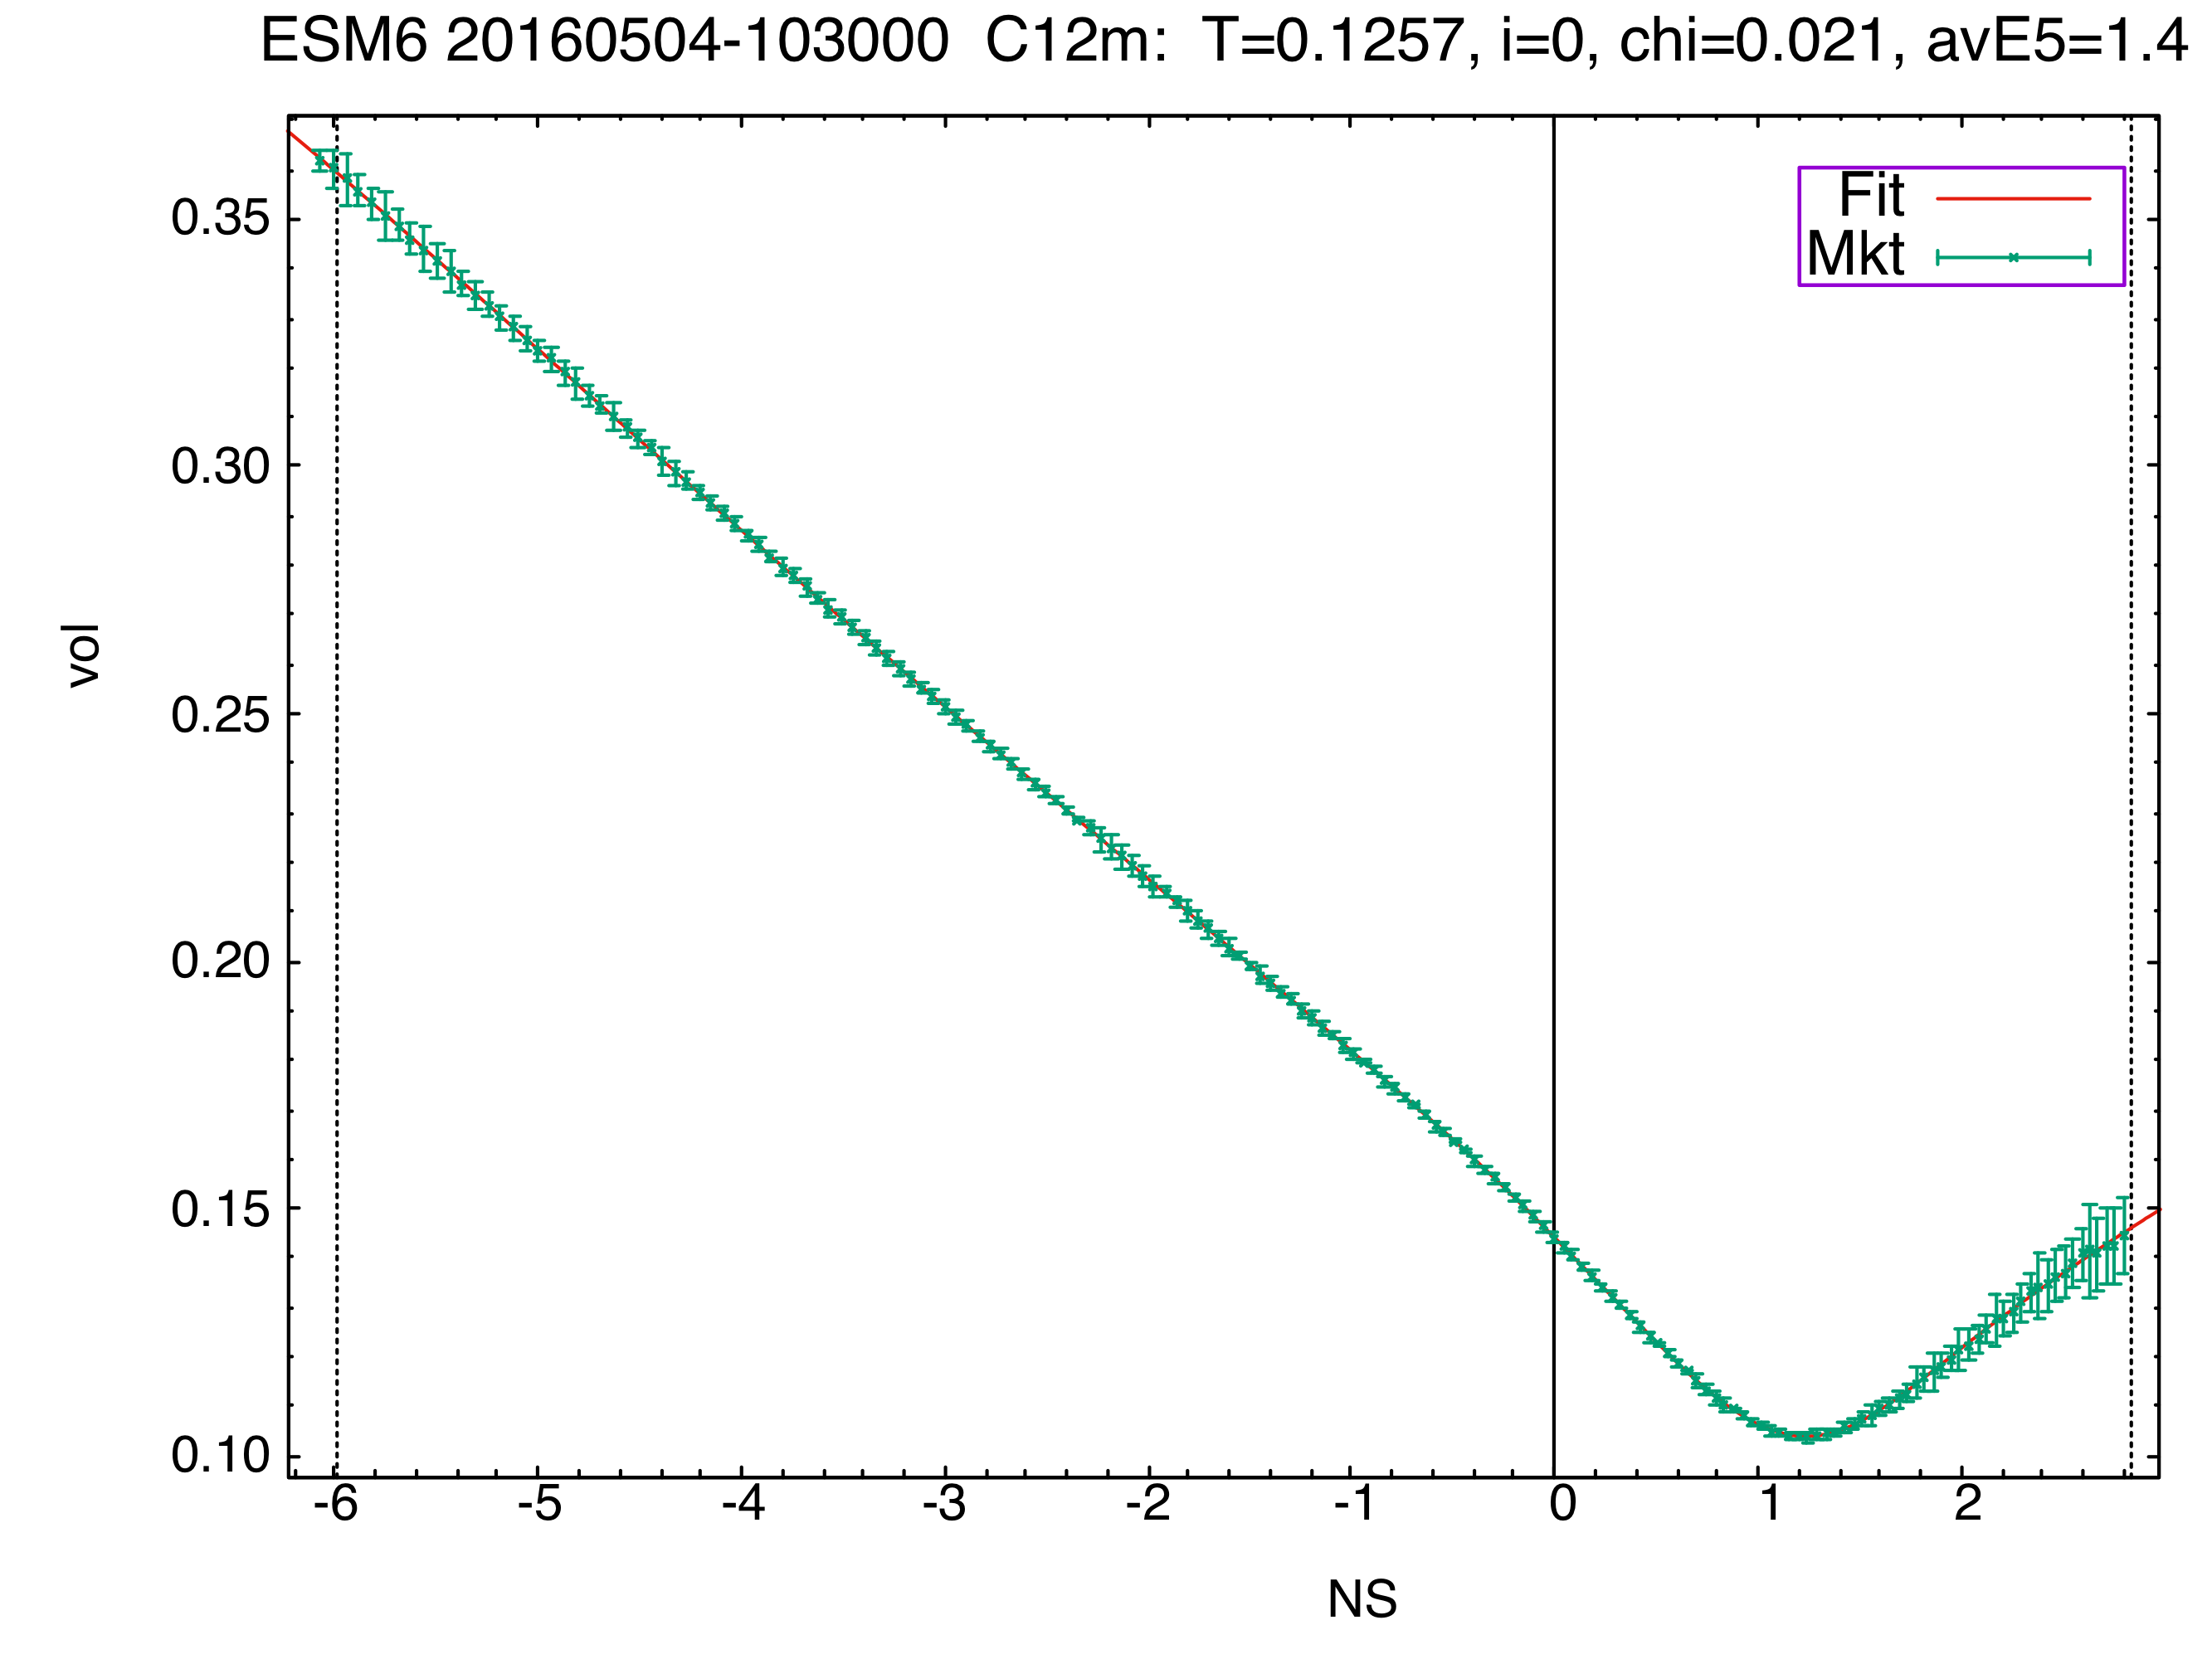
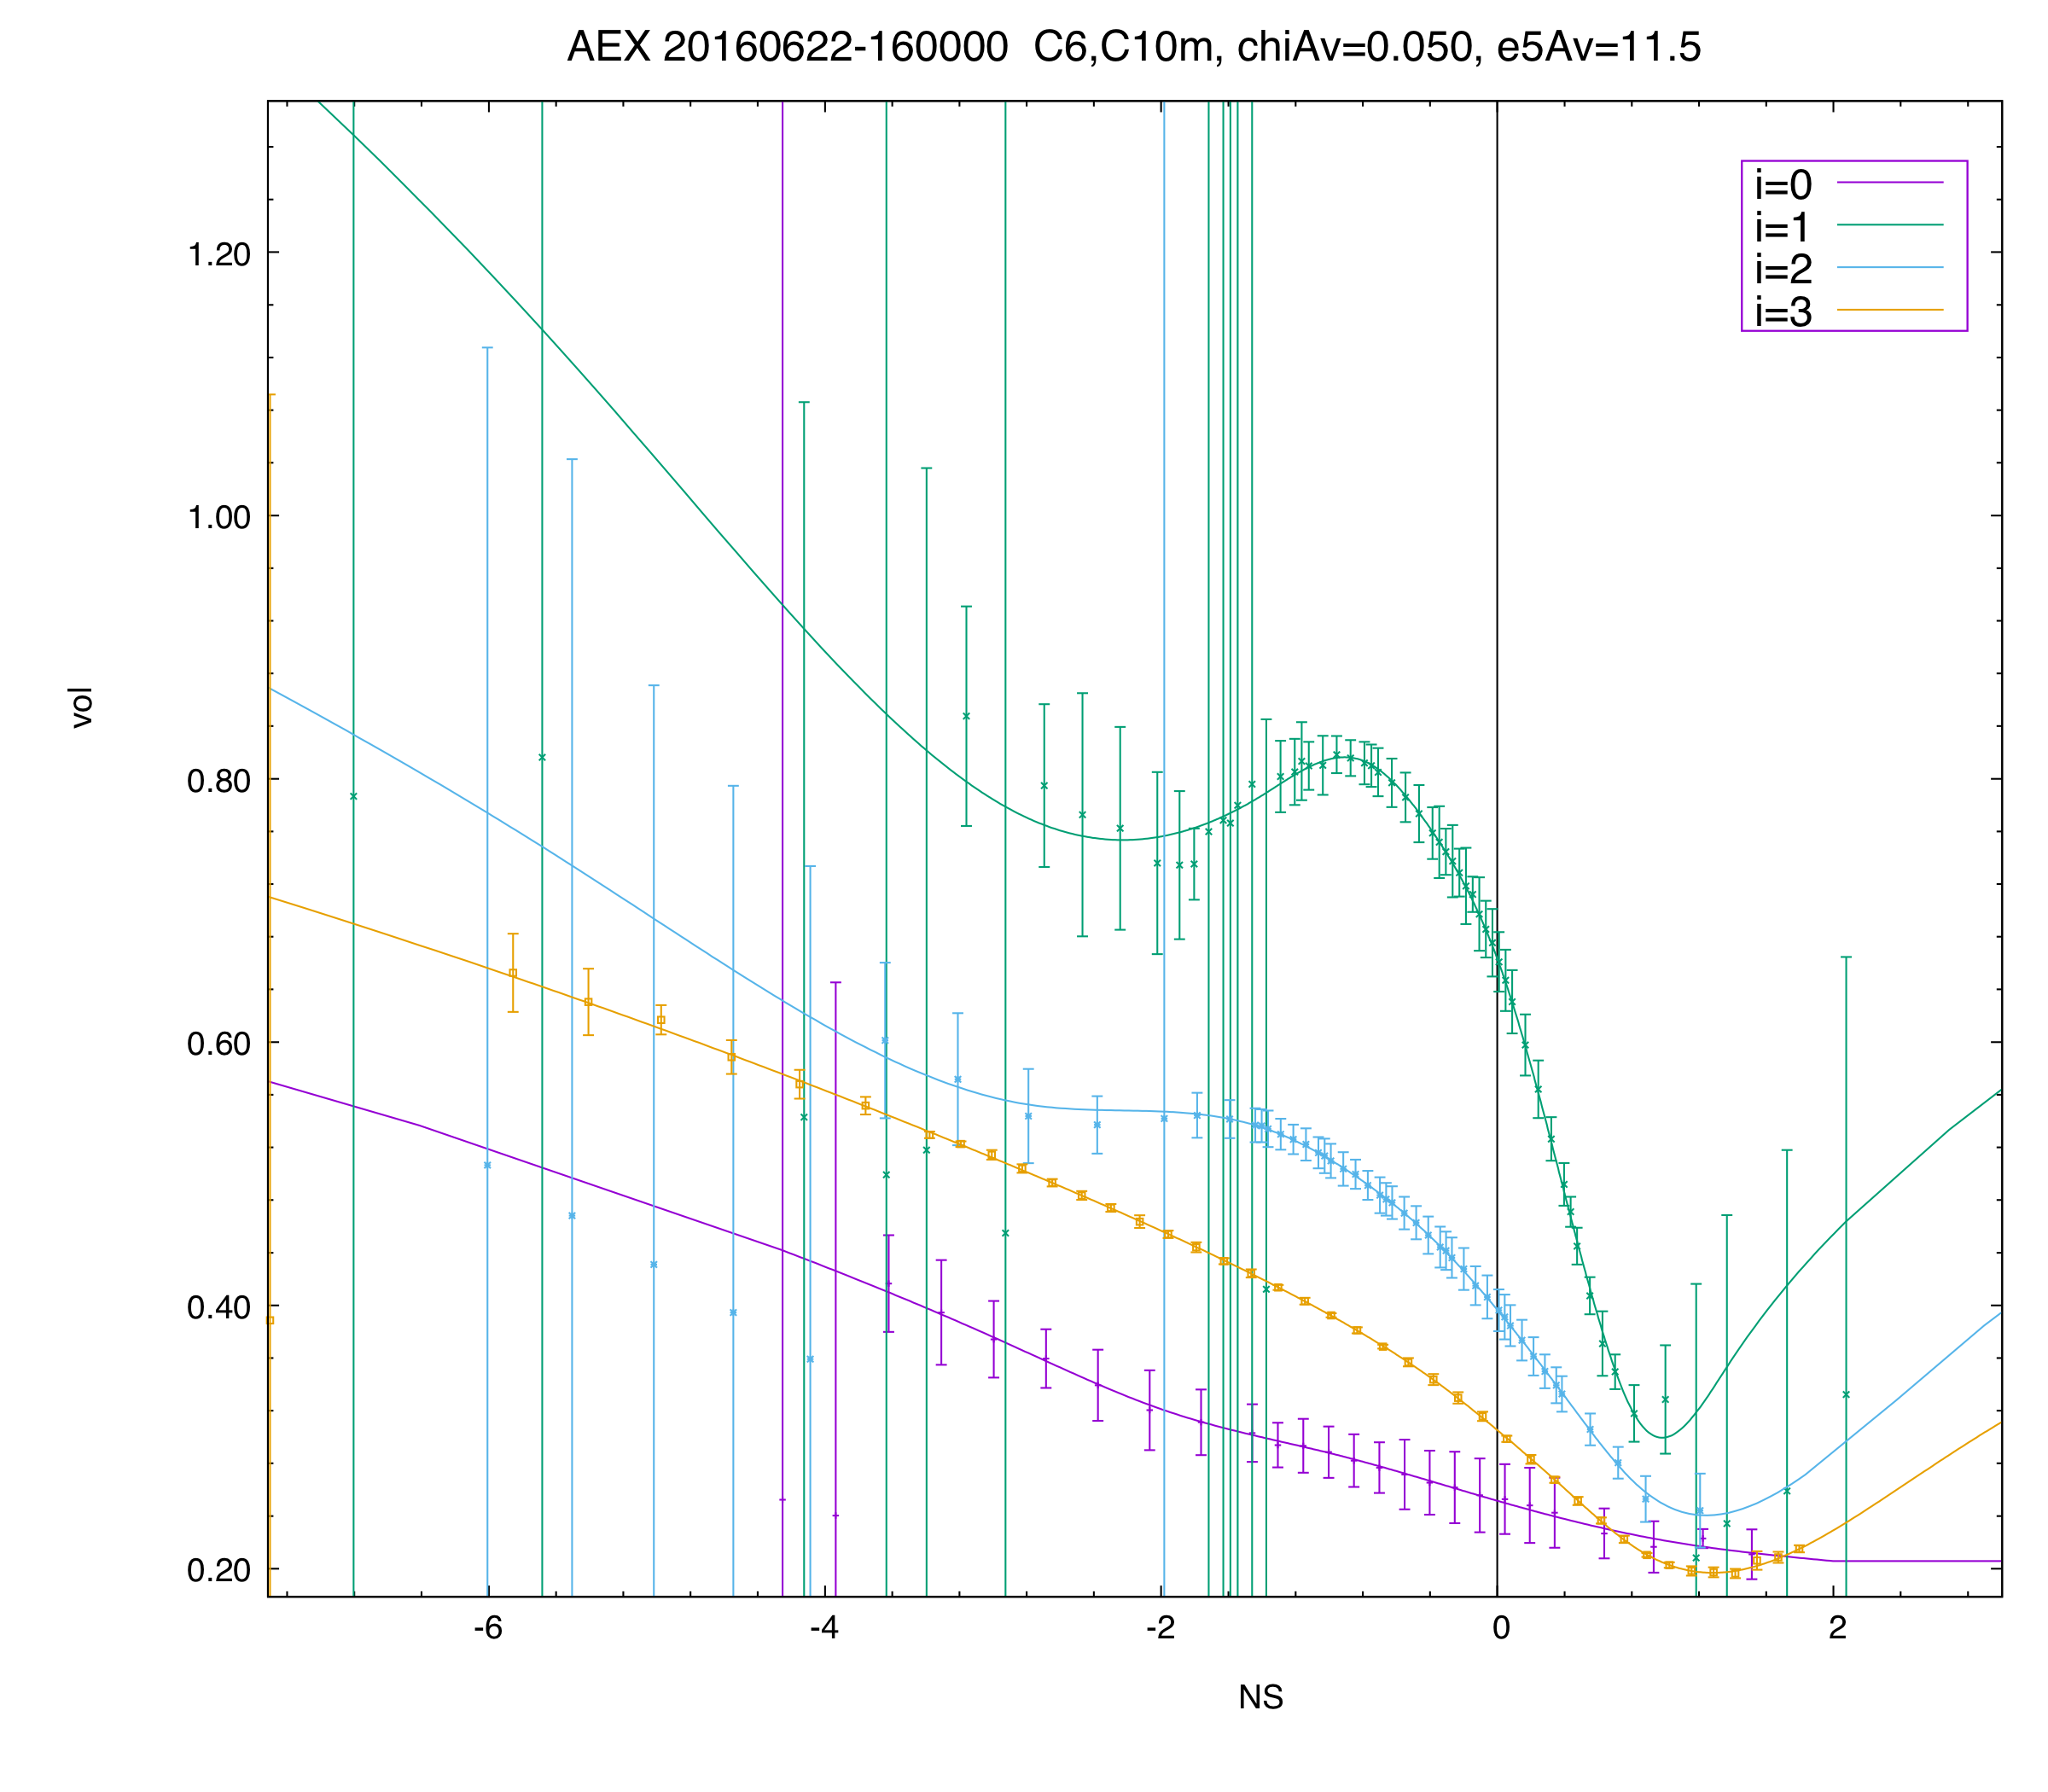
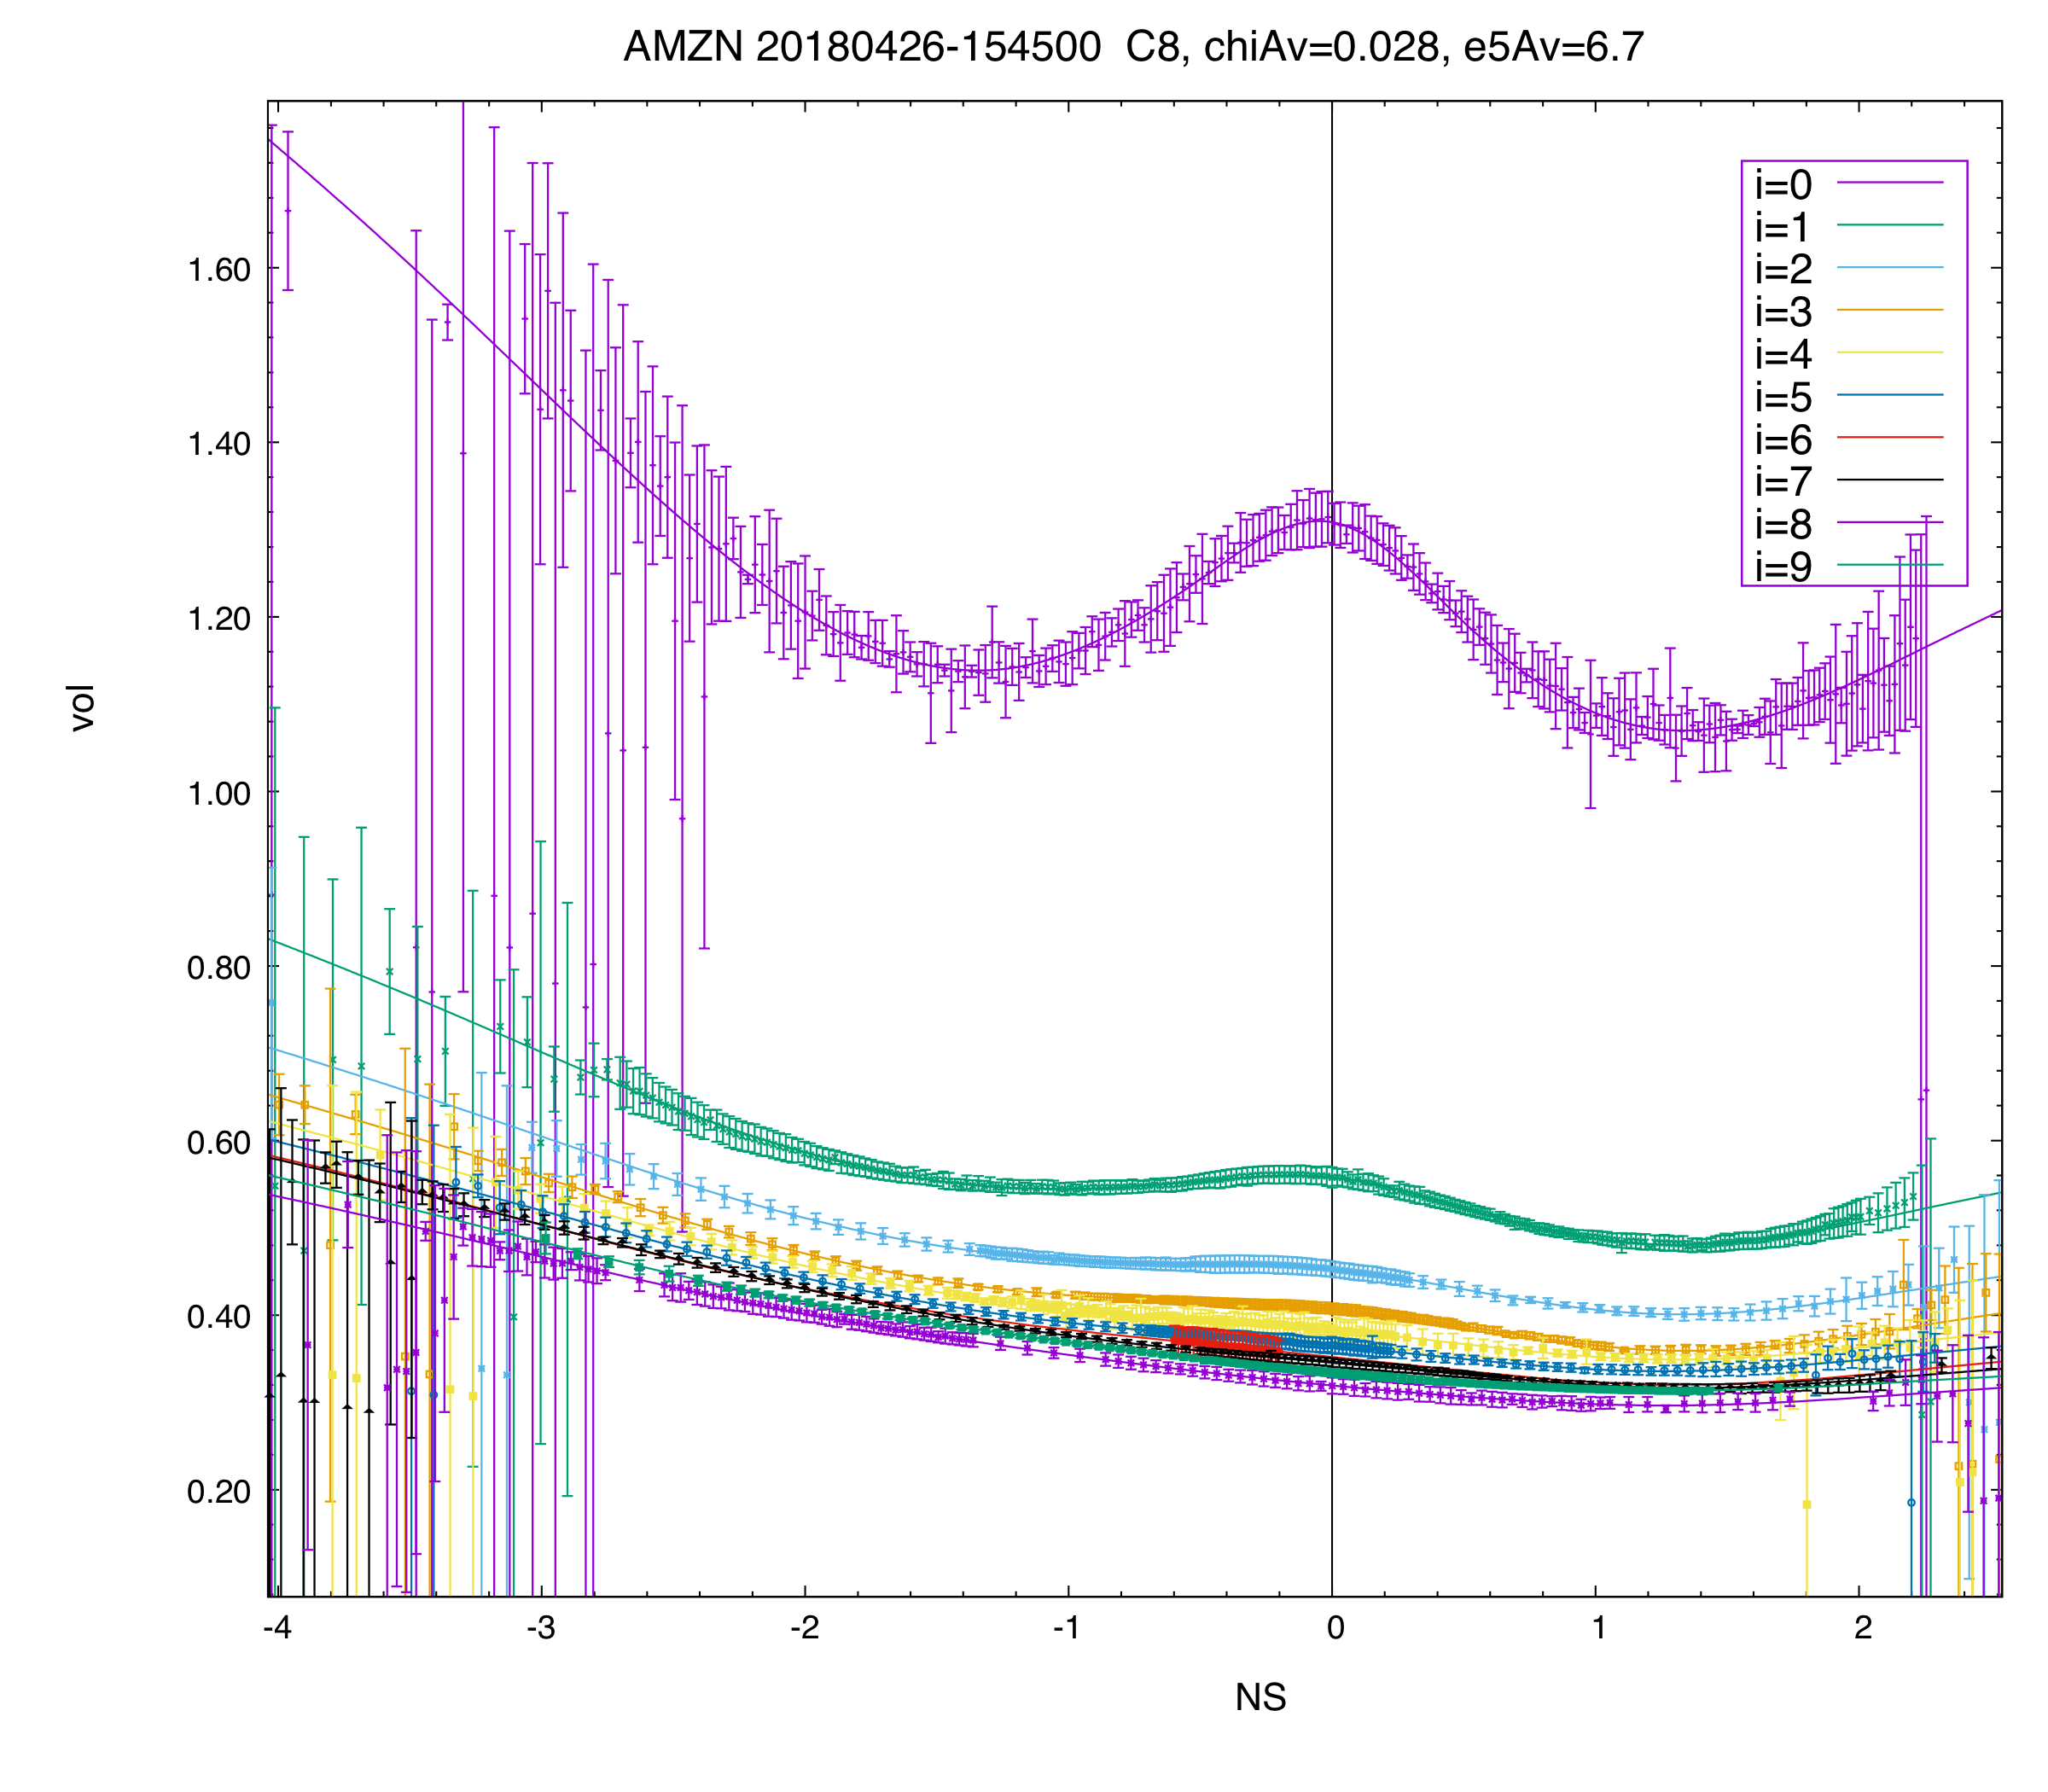
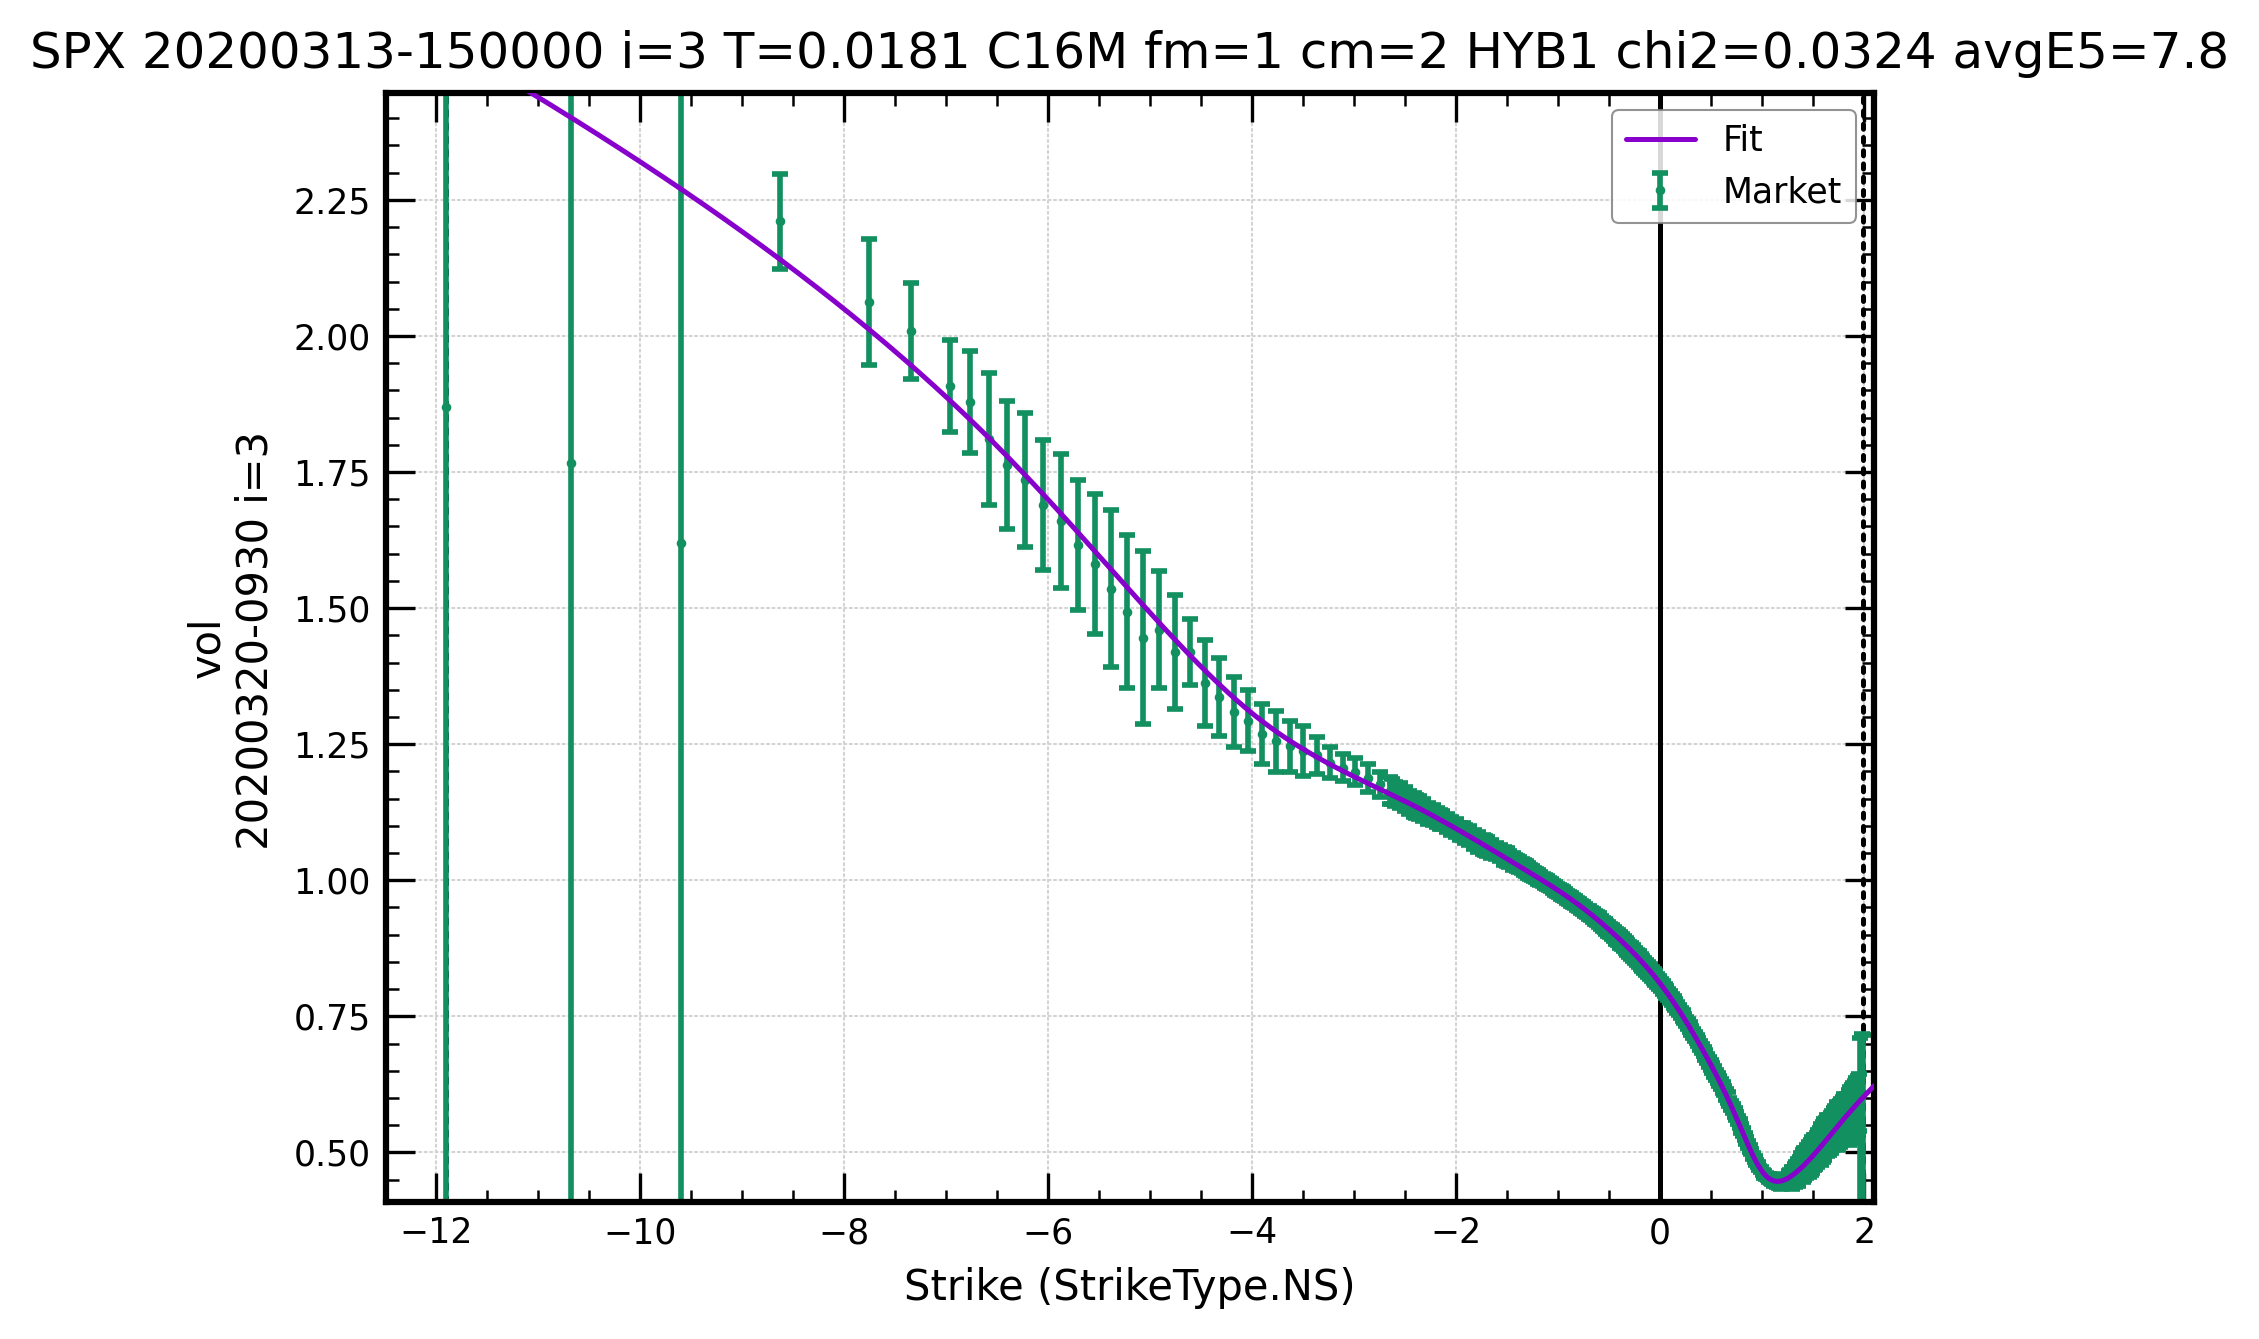
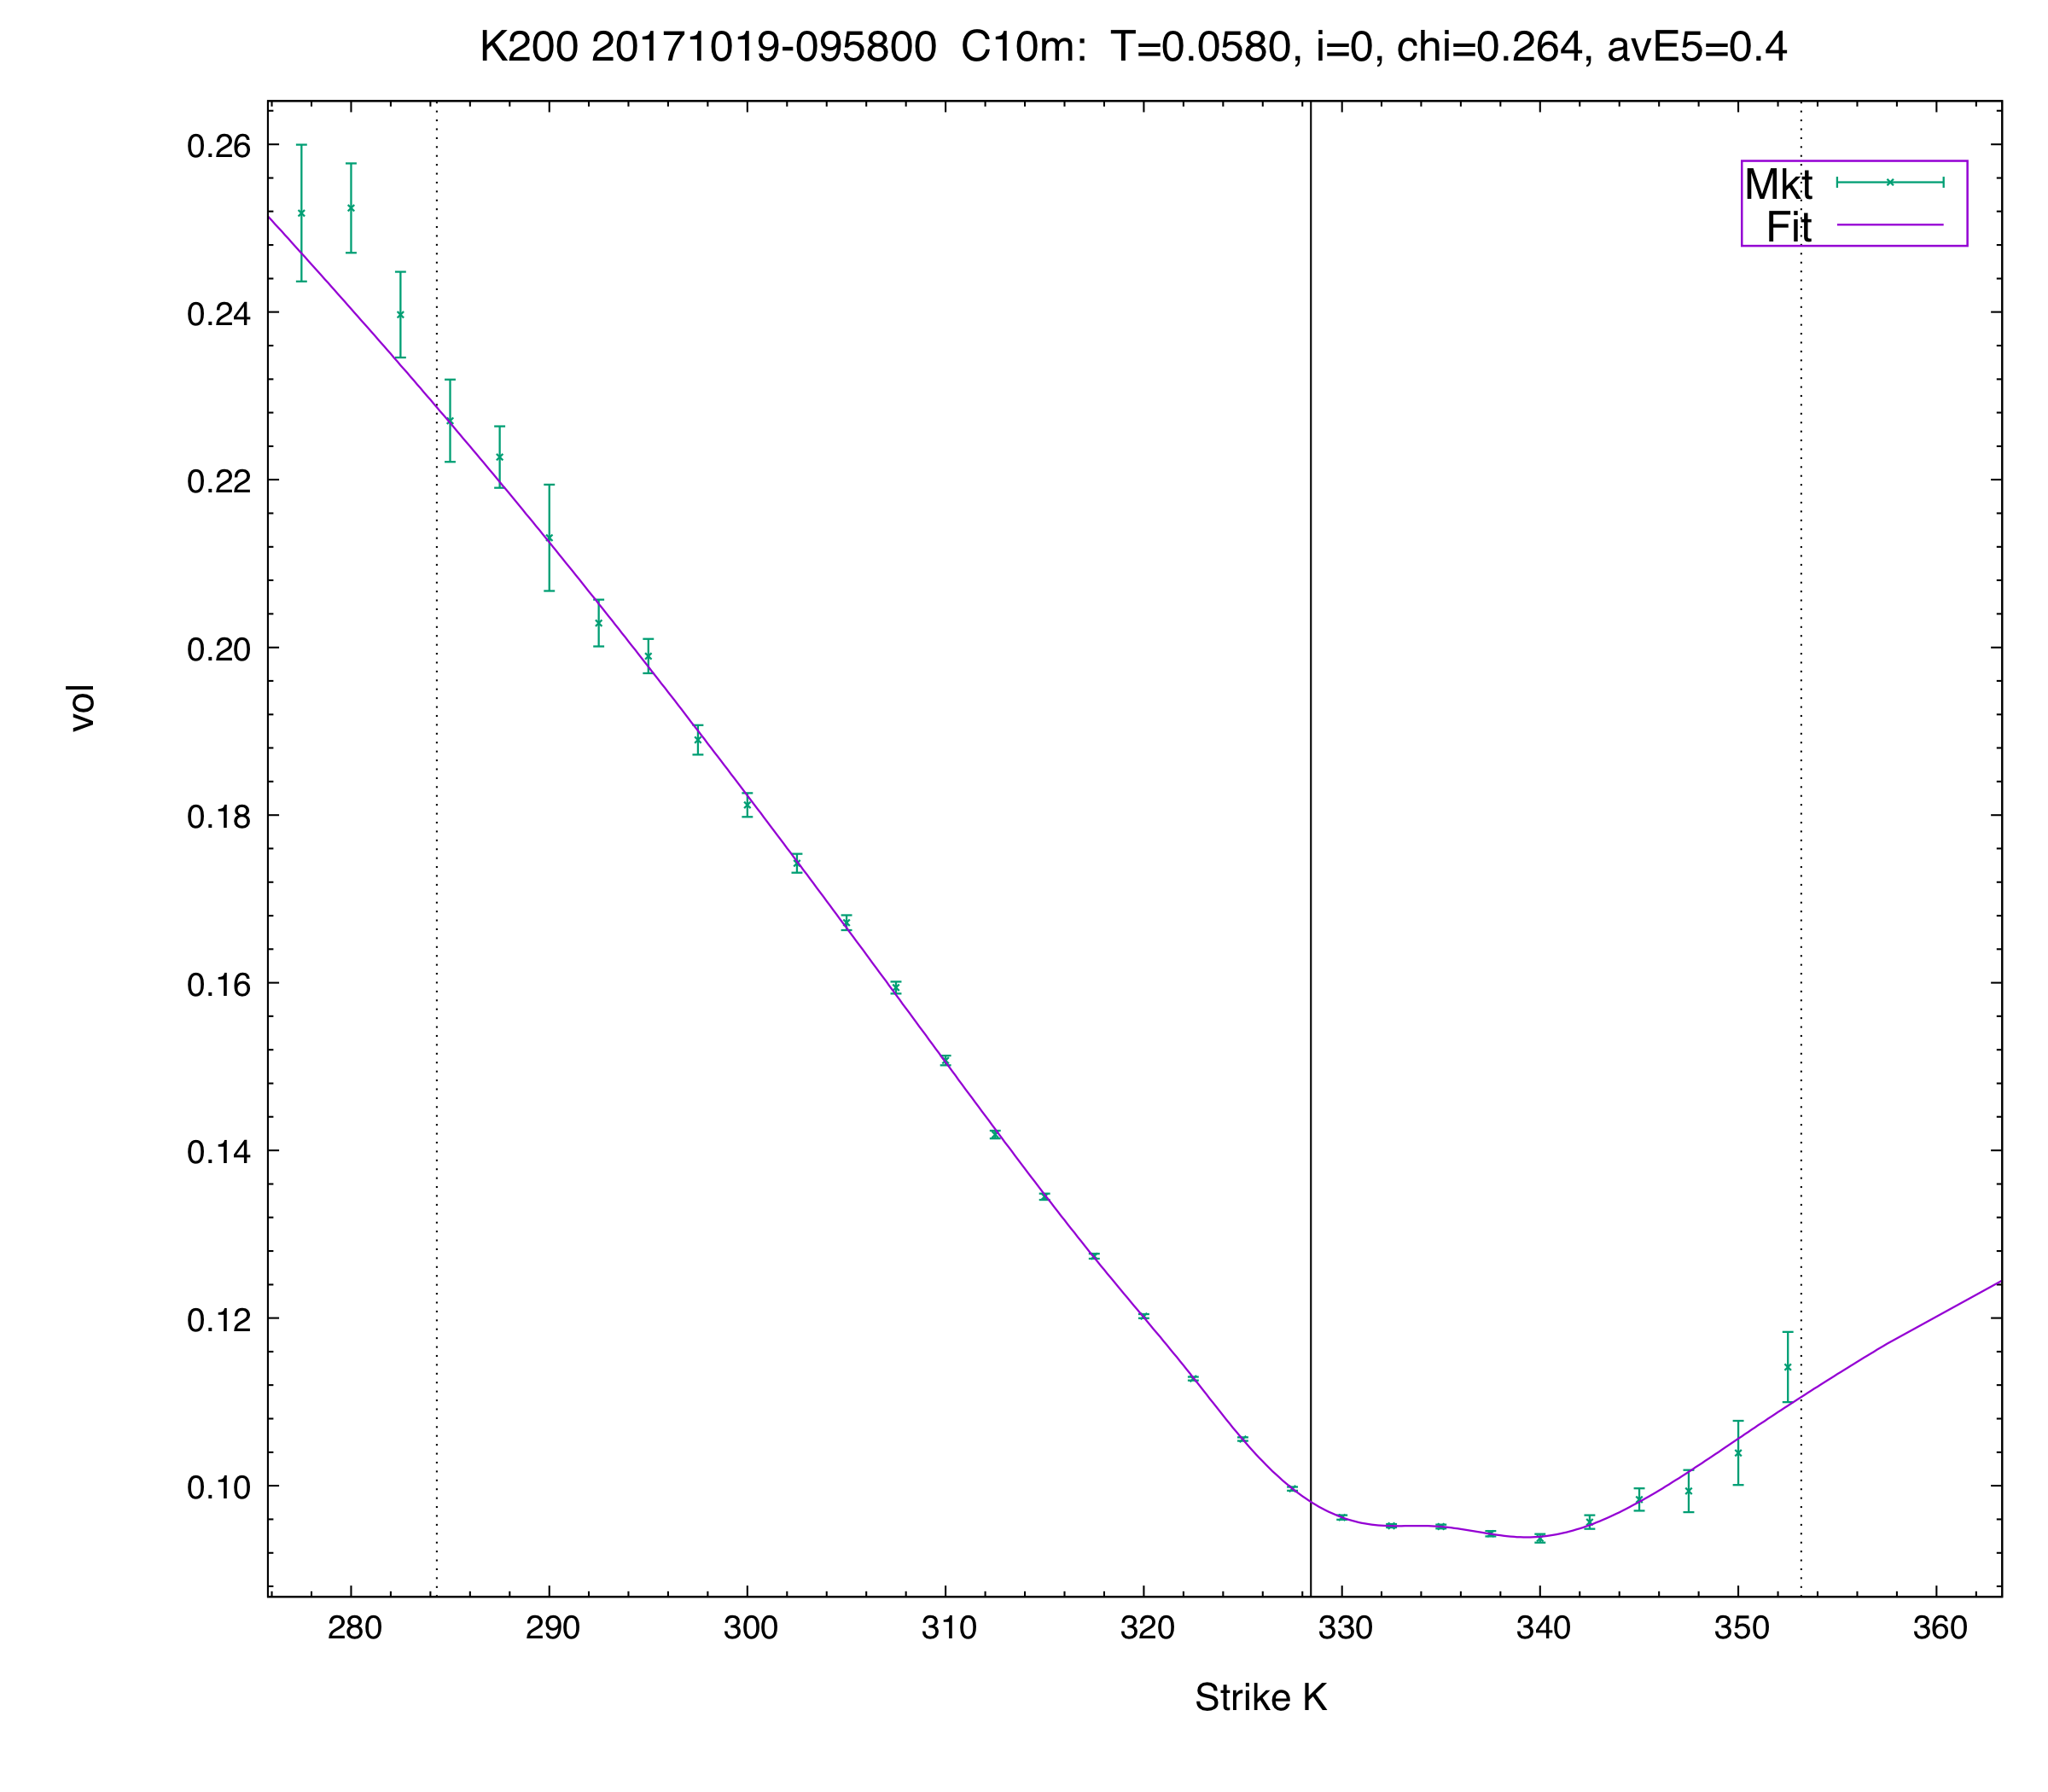
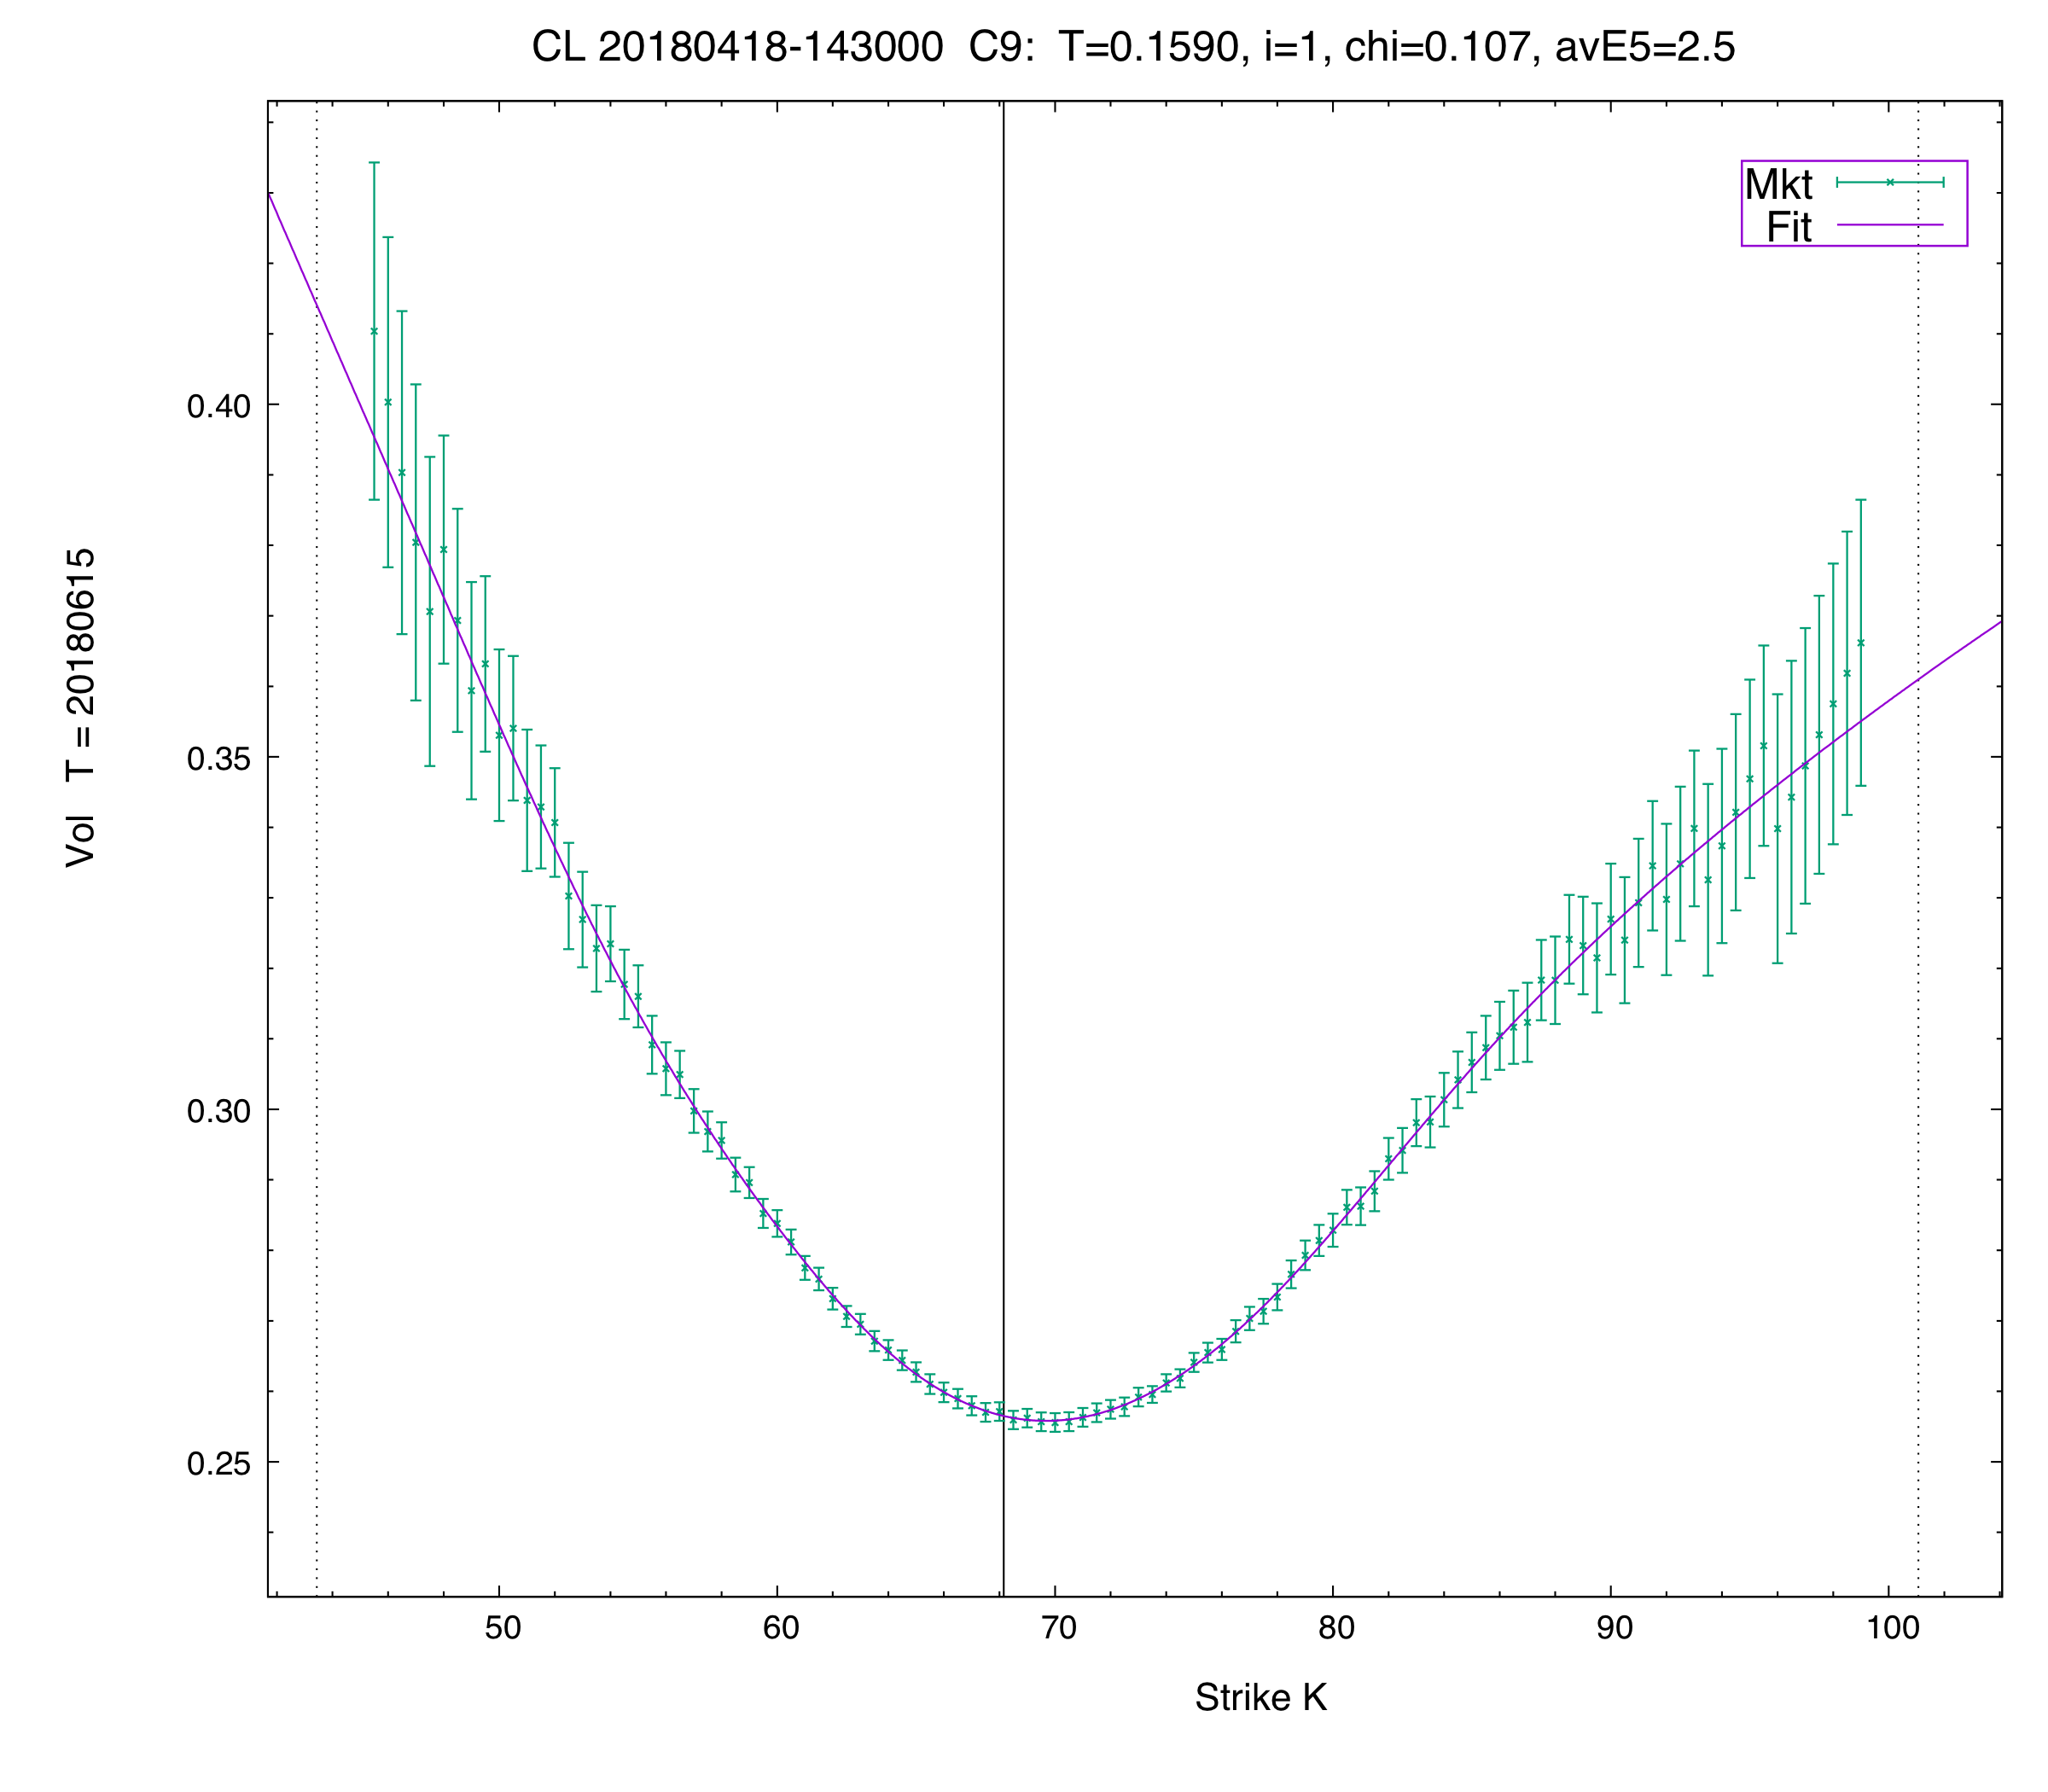
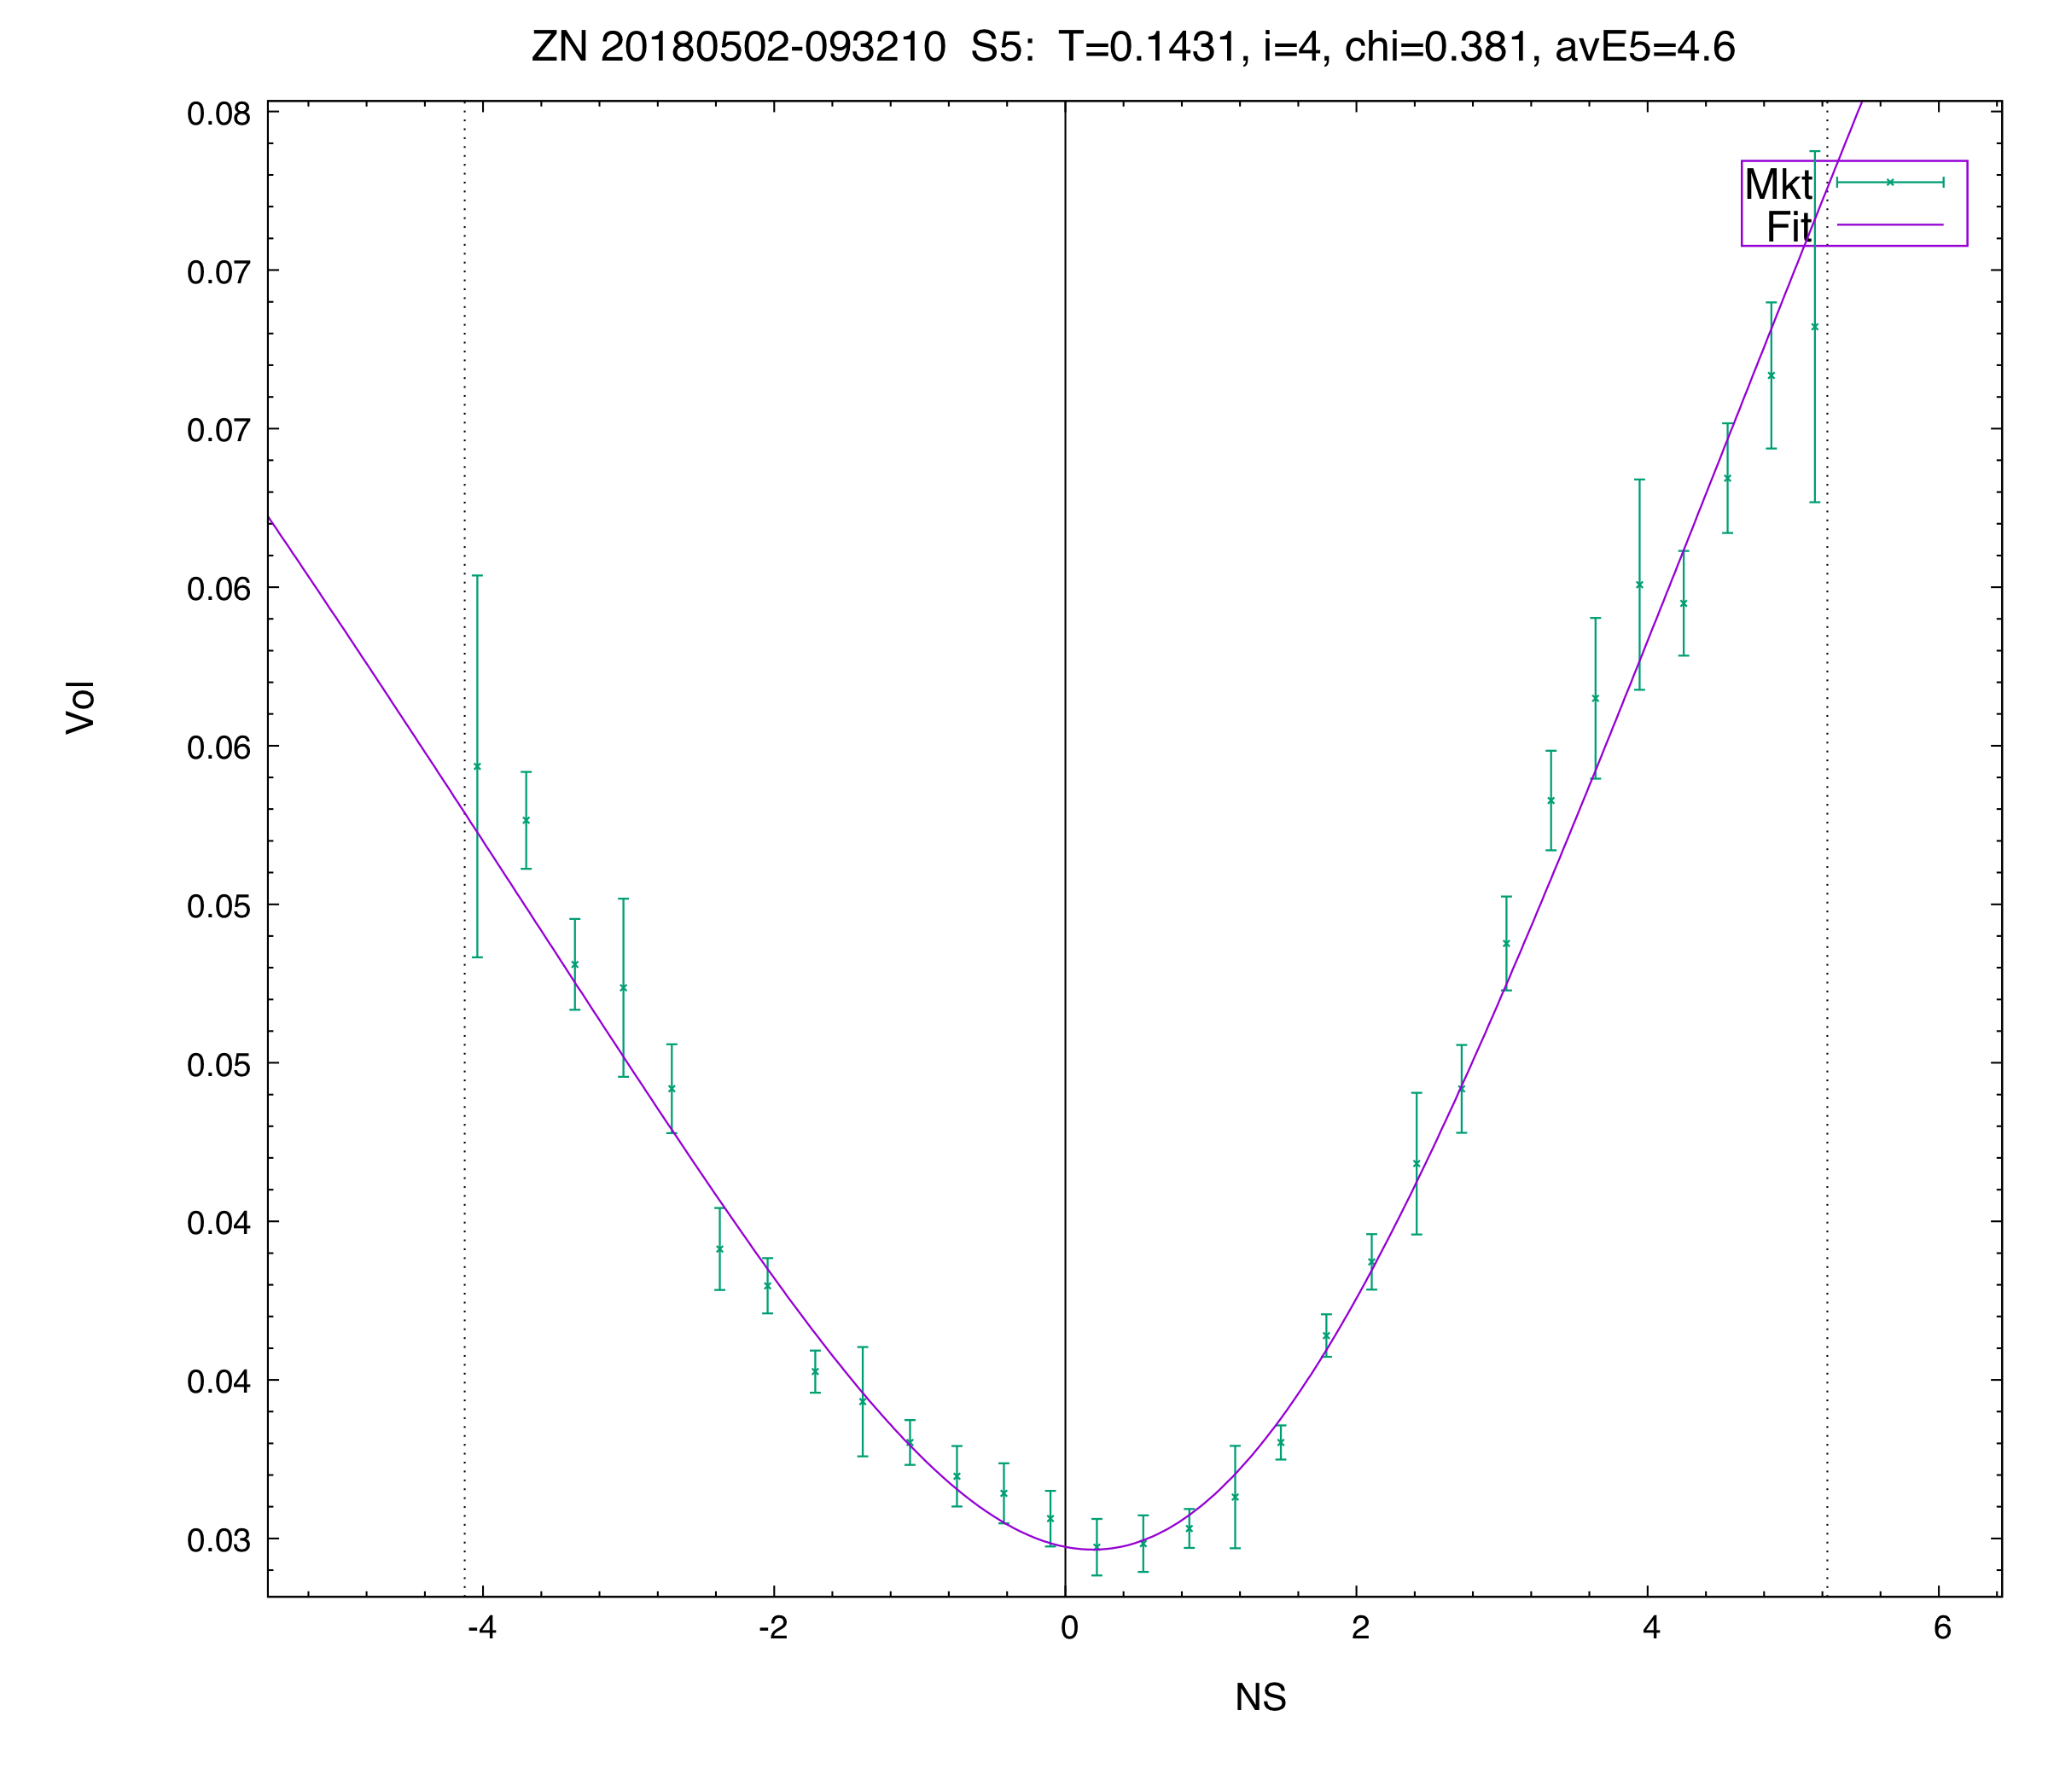
For Vanillas & vol derivatives (VIX, var, vol swaps)
Institutional Options Analytics



And 40+ other institutional options trading desks.
- Institutional clients
- ~50
- Client AUM
- >$900B *
- Founded
- 2016
* As of April 2026.
A Complete Volatility and Pricing Infrastructure
The surface informs pricing, pricing determines Greeks, Greeks drive hedging and PnL — and at every step, the requirements are in tension. Accurate and fast. Smooth and flexible. Robust and arbitrage-free.
-
Proper spot-vol dynamics
e.g. via "SSR", is integrated throughout, for accurate "smart" delta and gamma, realistic spot scenarios (incl. overnight), and temporal smoothing without bias.
-
Bias-free fits of arbitrary market vol shapes including W-shapes
Fit even the most liquid names like SPX, SPY, ES, NVDA, TSLA, etc, including around events or periods of market turmoil.
-
Intuitive and flexible parametric curves
Way beyond simple curves like SABR, SSVI, SVI (which are also available).
-
Cash dividend & forward modeling
Accurate and flexible, including "blending schemes", large borrows (HTB), funding curves, etc.
-
Implied borrow, forward and vol calculations
Fast, accurate and robust for any dividend model.
-
All greeks
Delta, gamma, vega, volga, vanna, rho, rhoBorrow, rhoDiv, thetas (with regard to rate or vol time), fugit.
-
Flexible temporal filtering and priors
Allow intuitive stabilization of vol surfaces even if data become very sparse over extended periods.
-
Vol surface shape transformations
Universal and intuitive across all curve types. Extend vol surfaces beyond listed expiries, or proxy to other names, etc.
-
Subtleties for modern markets
Rate term-structure pricing, vol-time, events, and settlement effects.
See how firms use Vola's institutional options analytics.
Supported directly by the quants who build it.
Beyond SVI & SABR
-
Flexible & Intuitive
Trade any index, ETF/stock, or futures options in any asset class (equity or FICC) off auto-fitted and/or easily adjusted surfaces.
-
Robust & Fast
Ultrafast market-maker-quality valuations and vol surfaces.
-
Easy Integration
Drop-in replacement for critical pricing and fitting infrastructure (C++, Python, Java, C#).
Built for options desks
Volatility Fitting & Options Pricing
- Ultrafast, robust options pricing with full Greeks
- Real-time borrow implication and volatility fitting for electronic trading
- Stable, arbitrage-free vol surfaces to feed into your local vol or stochastic local vol model
auto fa   = makeFactoryAnalytics();
auto fp   = std::string("AEX_20160622-160000.000-CET_ocpf-eq.json.gz"); // serialized price fitter
auto ocpf = fa->makeOptionChainPricerFitterEquity(fp);         // create fitter from serialized instance
auto oc   = ocpf->optionChain();                               // the option chain with contract information
auto ps   = ocpf->priceSnapshot();                             // price snapshot with price information
auto vcts = VecVCT{ VCT::C6, VCT::C10M };                      // curve type to use for fitting vols
auto rf   = ocpf->fit(ps, vcts);                               // fit price snapshot
auto vs   = rf->volSurface();                                  // use the volsurface for pricing
auto ocp  = fa->makeOptionChainPricerEquity(oc, vs)            // create pricer
auto rp   = ocp->price();                                      // compute prices and greeks for all options in the option chain
- C++
- Python
- Java
- C#
- Windows
- Linux
- OSX
Vol Surfaces, Greeks, PnL, Events & More
Base Package
-
Pricer
Vola Dynamics Pricer — super-fast and robust pricing of European and American vanillas, with accurate handling of cash dividends. Full Greeks including delta, gamma, vega, volga, vanna, rho, and theta.
-
Fitter
Vola Dynamics Fitter produces stable, arbitrage-free volatility surfaces using Bayesian methods. Fits the entire US options universe on one box — equities, ETFs, indices, and futures.
-
Curves
Vola Dynamics Curves — intuitive and flexible parametric vol curves, way beyond simple curves like SABR, SSVI, and SVI. Bias-free fits of all observed market vol shapes including W-shaped curves around earnings.
Trusted by Market Makers, Hedge Funds & Tier 1 Banks
Core valuation and risk analytics for equity, futures, and index options.
-
Your vol curves work like magic.
Quant trader @ Major European hedge fund -
Impressive library vastly superior to any other vendor product.
PM @ New York hedge fund -
Vola Dynamics has significantly improved our volatility fitting, particularly in handling earnings and dividend events. Their robust approach has enhanced our trading strategies and risk management capabilities.
Senior Quant @ Swiss investment group