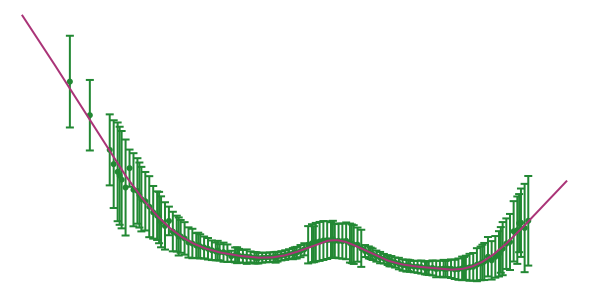
NDX · 3 May 2023 vol
Module
Fitter
- Super-fast and robust. Fit the whole US options universe on one box!
- Based on modern Bayesian ideas, superior numerics, and 30 years of trading and research. Robustness is achieved by transferring information across strikes, expiries and time (filtering).
- Uses unique set of flexible and intuitive curves (see Curves for details), allowing smooth and bias-free fits of all observed skews in the market.
- Adjust volatility surfaces between fits using proper spot-vol dynamics.
- The fitter can produce stable, arbitrage-free volatility surfaces even in the far wings, beyond the range of listed options, as required for the calibration of the various “SLVJ” models used for exotics and structured products.
- Output error bars derived from input bid-ask spreads quantify uncertainty in each fitted vol. For market makers, they serve as a natural “minimum edge” — if the market price is within the error band, there is no statistical confidence that edge exists.
- Graduated defense: when data quality degrades (stale quotes, exchange glitches, erratic markets), error bars widen automatically, making the system more conservative without hard kill switches.
- Battle-tested through the COVID crash (VIX > 80), GameStop short squeeze (500%+ IV), negative oil prices, and 0DTE — no manual intervention, no parameter tuning required. See examples.
- Handles 0DTE and daily expirations — where even small input errors produce large vol errors and the surface shape changes rapidly intraday.
See how market makers, hedge funds and banks use Vola’s volatility surface fitting in production.